
Grounded · Use cases
Thirteen questions, answered with receipts.
Every page here is one real question put to a fictional company and answered by the real app. You get the answer, the citation clicked open, and the trust chain under it. Pick your seat.
Check the board pack
"Does the cash in the May pack tie to the bank?"
Through the cashbook, one stale cheque flagged.
 Grounded
Yes, the May pack cash ties to the bank reconciliation arithmetically, but I need a reviewer decision on one stale item before I can mark the bank rec fully complete.
Reconciliation check:
Bank statement close: £9,882,613.23 per the May operating account statement 40
Less unpresented payments from the May bank rec:
- Cheque 004182 — Airedale Window Cleaning: £1,850.00, still outstanding at 12 Jun 14
- Expense claims batch: £23,412.77, cleared 1 Jun 14
- Supplier payment run: £1,191,437.29, cleared 1 Jun 14
Add uncleared lodgements:
- Customer remittances in transit: £161,309.55, cleared 1 Jun 1
- Card settlements: £84,166.20, cleared 1–2 Jun 1
Calculator check:
That agrees to the cashbook closing balance of £8,911,388.92 1, independently shown in the May cashbook extract as the closing balance c/f 19. It also rounds to the May Monthly Reporting Pack cash figure of £8,911k on the Balance Sheet basis 1.
Verdict: arithmetic TIES to the May pack, at £’000 rounding.
Checkpoint: Cheque 004182 for Airedale Window Cleaning is still outstanding and flagged as stale/review-required 14. Please choose: chase, reissue, or write back per policy. I’ve written the verification note to deliverables/bank-rec-verification-May-26.md with the decision pending.
Ask what if
"What is our cash runway, and what happens to it if the Phase 3 runs twelve months longer?"
Facts cited, assumptions written down, opinion last.
Recommendation: Use 37.7 months as the planning-case runway if FANFARE-2 / SFB-201 Phase 3 runs 12 months longer than planned.
Confidence: MEDIUM
As of the June 2026 close, Super Fancy Bio has $717.2M of cash, cash equivalents and investments, with $15.8M/month of YTD average net burn and 45.4 months of implied runway. 286 The schedule’s methodology assumes the YTD average burn continues and excludes the undrawn Stonebridge Capital facility. 287
For a 12-month FANFARE-2 extension, the best-supported planning case is an incremental $122.4M of CRO-related cash need: $5.9M/month of Tessern direct service fees plus $4.3M/month of pass-through costs, for 12 months. 162 That would consume about 7.7 months of runway at the current burn rate, reducing runway from 45.4 months to roughly 37.7 months. 286
I would also track sensitivities:
- Floor case: about 41.3 months of runway, assuming only recurring project/site costs continue. 155172
- Downside all-in program case: about 32.5 months, using recent FANFARE-2 program spend as a proxy. 308309310
The assumptions to challenge are: whether the 12-month delay should include only CRO direct/pass-through costs; whether CMC, internal FTE, lab, site, patient, and closeout costs are incremental; and whether the current YTD burn rate is the right denominator for runway planning.
The full advisory report is saved in the workspace as advisory-report.md. Happy to walk through the math, the sensitivity cases, or what management should request before approving an extension budget.
The audit trail
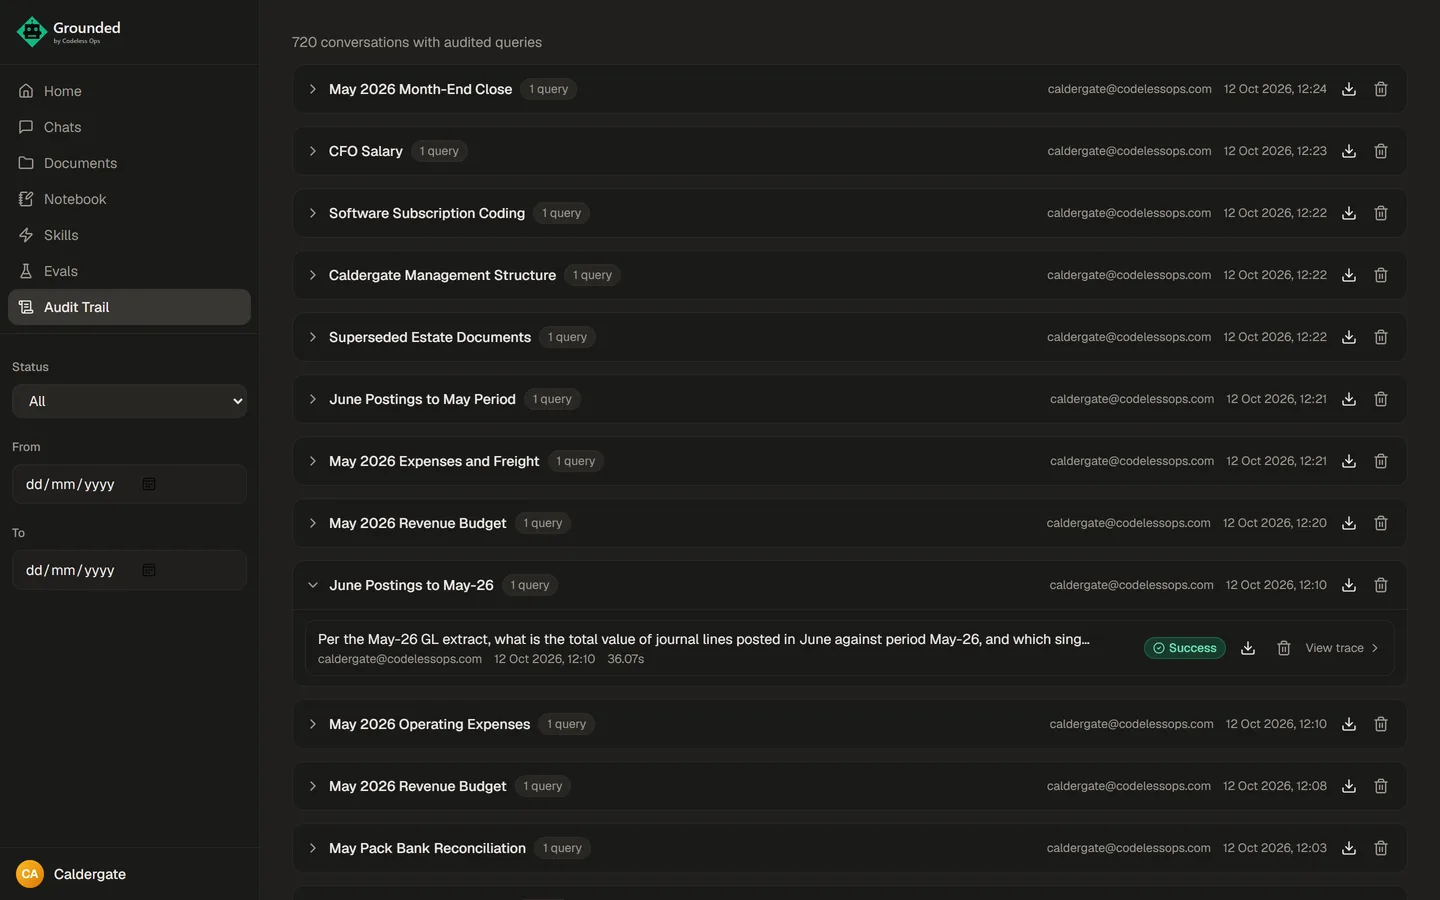
"Open the audit package for the March bank reconciliation answer."
An answer from March, reopened in September, sources intact.
Ask it from Slack or Claude
"@grounded what was the total revenue in May 2026 vs budget?"
The same cited answer, wherever you happen to be.
Do these two reports agree?
"Do the December FY26 route results agree with the MTD P&L on year-to-date total operating expense?"
$1.4M apart, both cells cited, the reason found in a contract.
NEAR-MISS — they do not quite agree. The December FY26 Route Results show YTD SSR total operating expense of $1,158.1M 169170, while the MTD P&L shows YTD total expense of $1,159.5M 171172: a $1.4M gap.
| Line item | Route Results by Service Line - 1225 | MTD P&L - 1225 | Difference |
|---|---|---|---|
| YTD Dec FY26 total operating expense | $1,158.1M | $1,159.5M | $1.4M Σ |
Materiality: $1.4M on the larger reported value of $1,159.5M = 0.12%.
Likely cause shown in the notes: there was a known December/January timing issue around the Meridian winter-cycle true-up: the central P&L accrual route was considered fine, but late items could slip the route-level extract, especially on “Non-Corridor Special Trains & Adjustments” 24. Since the MTD P&L is the anchor when reports disagree, I would treat the P&L as the control total and follow up on the route extract.
Easy queries
"What was revenue for May 2026, against budget?"
One cell, one click to check it.
May 2026 revenue was £21.063m actual versus £20.753m budget, a £0.310m favourable variance. The pack is stated in £’000, and variances are actual less budget. 3637
Hard queries
"Per the May-26 GL extract, what is the total value of journal lines posted in June against period May-26, and which single item accounts for most of it?"
Four documents, one answer.
Per the May-26 GL extract, the journal lines posted in June against period May-26 total £333,173 Σ.
The single item accounting for most of it is JNL-508295, the £285,000 accrual for the Ridgway Freight May invoice received after ledger cut, posted on 2026-06-10 to Carrier & freight charges / Warehouse & Logistics. The other June-posted May-26 lines are much smaller: Digital media retainer, Advisory fees, and SaaS subscriptions. 59606162
The 4:45 Friday question
"For May 2026, what was total department operating expense, and how did Warehouse & Logistics carrier and freight charges compare to budget?"
The variance the CFO wants before the weekend, with the cell.
Using the May-26 Monthly Reporting Pack as the governing issued pack:
| Metric | May-26 actual | May-26 budget | Variance |
|---|---|---|---|
| Total department operating expenses | £4,832k | £4,805k | £27k adverse |
| Warehouse & Logistics — carrier & freight charges | £336k | £328k | £8k adverse |
The pack states figures are in £’000 and that department totals tie to the operating-expense lines of the Consolidated P&L, excluding depreciation and amortisation 737475. For Warehouse & Logistics, carrier & freight charges were £336k vs £328k budget, i.e. £8k over budget 5051. The May commentary notes the £336k includes a £285k accrual for a late carrier invoice received after the ledger cut 27.
Which version is real
"Are there any documents in this estate that supersede others, anything I should never cite?"
April v1 or v2 FINAL. The one marked FINAL, and it says so.
Yes. The estate has a clear document-authority hierarchy and a few “do not cite / cite with care” traps.
| Item | Status / rule | What to cite instead |
|---|---|---|
| Monthly Report - Apr-26 (v1).pdf | Never cite. It was superseded by Monthly Report - Apr-26 (v2 FINAL).pdf. The notebook explicitly says “Never cite v1,” and the v2 report says it supersedes the earlier version. 431 | Monthly Report - Apr-26 (v2 FINAL).pdf. Later YTD figures follow the FINAL version. 31 |
| Any reissued report not marked FINAL | The estate-wide rule is: a report marked FINAL supersedes earlier issues; later YTDs follow the FINAL copy. 18 | The copy marked FINAL, checking issue dates/header/file properties. 1819 |
| Working exports / standalone exports when they disagree with the pack | Do not cite them as governing numbers where they differ from the issued pack. The issued Monthly Reporting Pack is the record; exports can cut earlier and miss late journals. 7144142 | The issued Monthly Reporting Pack, especially the Consolidated P&L / relevant pack tab. 7 |
| Opex by Department standalone export | Cite with care only as a working export. There is a known gap versus the issued pack because exports can miss late journals; the issued pack governs. 1011 | The issued pack’s Opex by Department tab / Monthly Reporting Pack. 7 |
| Headcount & Cost Tracker (legacy).xlsx | Treat as non-authoritative / do not cite for headcount or cost conclusions. The company notebook says it carries a stale plan-basis footnote and is explicitly titled “Legacy headcount tracker — do not cite.” 16 | For headcount, use the monthly pack’s Opex by Department tab or the monthly HRIS extract. 17 |
| Plan columns: Budget / LF1 phasing | Never quote plan-column figures as actuals. Months after the latest close exist only as Budget or LF1 phasing, not actuals. 394950 | Use actuals only from closed/issued reporting packs; use Budget or LF1 only when explicitly discussing plan/forecast. |
Short version: use the issued Monthly Reporting Pack as the anchor; use FINAL reissues over earlier versions; never cite Apr-26 v1; avoid the legacy headcount tracker as authority; and never present Budget/LF1 plan columns as actuals.
Run the close
"Kick off the May 2026 month-end close."
Flash, journals, accruals, bank rec, variance pack, with you at every gate.
The May-26 pack is already issued: the May Monthly Reporting Pack shows reporting period “May-26,” issued on 10 June 2026, with status “Final” 2021. I’ll therefore frame this as a re-run of the May close checks and verification of the issued pack, not as a first-time close. The calendar says the WD8 issued Monthly Reporting Pack is the governing pack, and any later copy marked FINAL supersedes prior versions 27.
May-26 close checklist — table of record
| WD | Task | Owner | Output | Status |
|---|---|---|---|---|
| WD1 | Sales ledger and despatch cut-off; order-line despatch data frozen | Dev Patel, AR & Credit Lead | Frozen revenue subledger | Not started in this re-run |
| WD2 | Purchase ledger close; agency labour and carrier & freight accruals posted | Marta Kowalska, AP Lead · Ben Tranter, Management Accountant | Accruals in GL | Not started in this re-run 16 |
| WD3 | FLASH: headline revenue and gross margin issued to CEO & CFO | Priya Nair, FP&A Analyst | Flash email — not a governing document | Not started in this re-run 5 |
| WD4 | Segment reviews: GMs confirm revenue by channel and flag one-offs | Helen Drummond + segment GMs, with FP&A | Confirmed segment view | Owner step — not automated 24 |
| WD5 | CLOSE COMPLETE: manual journals posted and approved; GL locked | James Whitfield, Financial Controller | Locked GL for the period | Not started in this re-run 17 |
| WD6 | Pack drafting: Consolidated P&L, Revenue & KPIs, Opex by Department, Balance Sheet, Cash Flow | Priya Nair, FP&A Analyst | Draft Monthly Reporting Pack | Not started in this re-run 25 |
| WD7 | Controller review; commentary drafted with segment GMs; checks tab cleared | James Whitfield + Priya Nair | Reviewed pack, commentary | Owner step — not automated 26 |
| WD8 | MONTHLY REPORTING PACK ISSUED — Status: Final | Issued by FP&A after Controller sign-off | Governing pack — PDF + xlsx | Already issued; to verify 27 |
| WD9 | Variance follow-ups with department budget owners | Ben Tranter, Management Accountant | Actions list | Owner step — not automated 28 |
| WD10 | Quarter-ends only: KPI & Commentary Pack and board deck preparation begins; covenant certificate prepared | FP&A · Financial Controller | Quarterly outputs | Not applicable unless quarter-end close output is requested 6 |
Close board
The board is a visual of the cited checklist above. Bank reconciliation is included as a skill-added close check; it is not shown as a separate row in the close calendar.
Runnable close steps mapped to skills
| Calendar step | Skill |
|---|---|
| WD2 / WD5 accrual completeness | accrual-completeness-sweep |
| WD3 flash | wd3-flash-report |
| WD5 manual-journal approvals | journal-approval-check |
| Bank reconciliation | bank-reconciliation-close |
| WD6 variance pack + commentary | month-end-variance-pack |
The other calendar steps stay with their named owners.
Shall I run these in order? I’ll stop for your sign-off at each gate.
A new user coming in
"How is Caldergate's management structured? Show it as a diagram if that helps."
Drawn and cited.
Caldergate’s management structure is shown as a group executive team led by Robert Calder, CEO. Beneath him are five functional directors, who are also the budget owners for the five cost centres: CFO/G&A, Operations/Warehouse & Logistics, Commercial/Sales & Account Management, Procurement & Merchandising, and IT & Digital. 3420 Segment general managers report to the Commercial Director, while the three depots — Leeds NDC, Bristol RDC and Glasgow RDC — report to the Operations Director. 2122 The finance team sits under the CFO, with controller, FP&A, management accounting, AP, AR/credit and payroll roles; controller-side work covers close/journals/statutory/covenants, while FP&A owns the pack, flash, budget and LF1. 343536
Caldergate Distribution Group Ltd
└── Robert Calder — Chief Executive Officer
    ├── Sarah Okonkwo — Chief Financial Officer
    │   ├── G&A / CC-50 budget owner
    │   └── Finance team
    │       ├── James Whitfield — Financial Controller
    │       ├── Priya Nair — FP&A Analyst
    │       ├── Ben Tranter — Management Accountant
    │       ├── Marta Kowalska — AP Lead
    │       ├── Dev Patel — AR & Credit Lead
    │       └── Joan Pickering — Payroll Administrator
    ├── Marcus Webb — Operations Director
    │   ├── Warehouse & Logistics / CC-10 budget owner
    │   └── Depots
    │       ├── Leeds NDC
    │       ├── Bristol RDC
    │       └── Glasgow RDC
    ├── Helen Drummond — Commercial Director
    │   ├── Sales & Account Management / CC-20 budget owner
    │   └── Segment GMs
    │       ├── Tom Askey — GM, Facilities & Safety Supplies
    │       ├── Rachel Vine — GM, Industrial Consumables & Packaging
    │       └── Daniel Mercer — GM, Office & Print Solutions
    ├── Laura Bexley — Procurement & Merchandising Director
    │   └── CC-30 budget owner
    └── Sanjay Rao — IT & Digital Director
        └── CC-40 budget owner

Also shown within G&A:
└── Fiona Marsh — HR & Corporate Services
Commercially, the three segment GMs own revenue by segment, and each segment sells through the same three channels: contract & framework, spot & project, and trade counter & online. 2141
Cheat sheets in one place
"The sales team wants a new software subscription. Which account and cost centre does it get coded to?"
Coding, approvals, the glossary, the calendar. One box.
Code it to:
- Account: 7410 — Software licences & SaaS
- Cost centre: CC-40 — IT & Digital
Even though the sales team will use it, the cost centre map says software licences & SaaS sit in IT & Digital, and the analyst note confirms software goes to 7410/CC-40 no matter whose team uses it. 114
It says no
"What is the CFO's salary?"
It gives no figure, makes no guess, and explains why.
I couldn’t find the CFO’s salary in the available documents. The documents identify Sarah Okonkwo as the Chief Financial Officer, but the relevant governance/authority policy explicitly says it contains no salary or remuneration data 192832.
Fictional companies (Caldergate Distribution Group, Super Speedy Rail, Super Fancy Bio), real app, captured on the dates shown.
Hiring?
Need this kind of build on your team?
I take contract roles in finance automation and FP&A systems. Ask me anything about how Grounded works; I'm happy to walk through the parts that broke as well as the parts that worked.